

Selling a business
Selling a restaurant or food service business
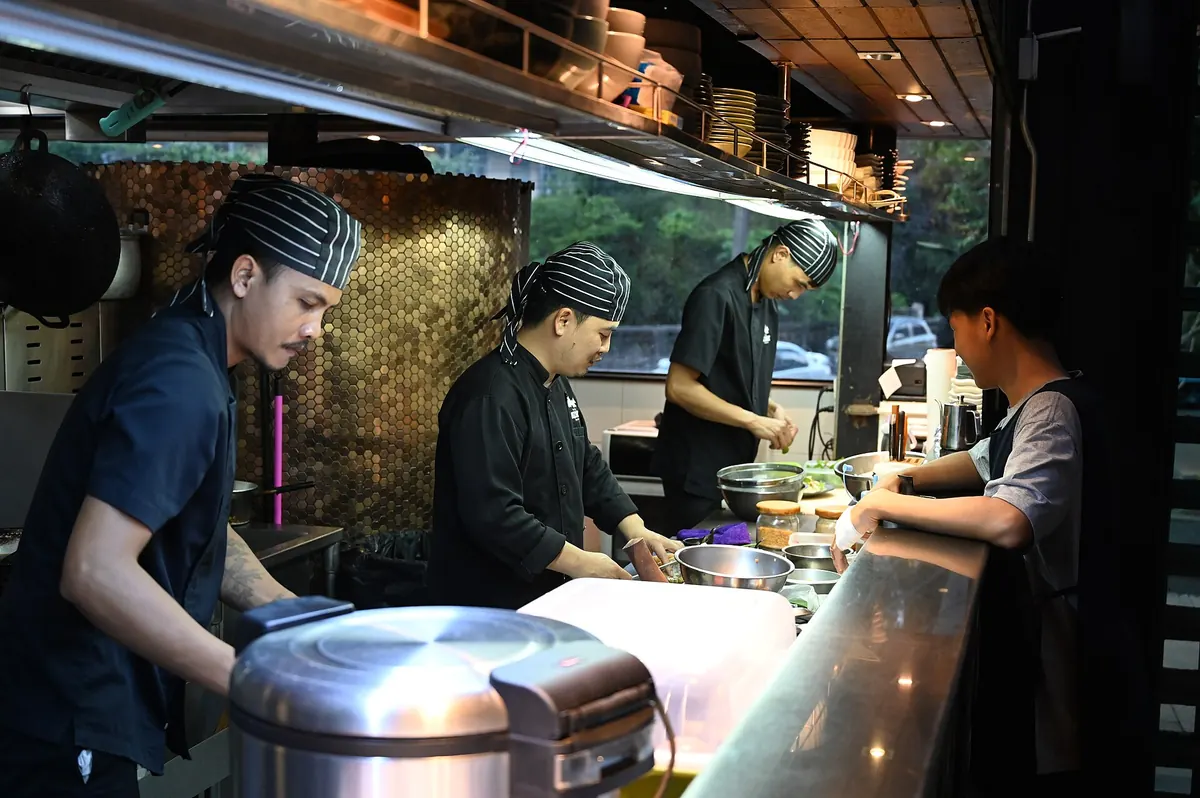
Restaurants, cafés, bakeries and catering. In food, the lease is often the biggest asset you’re selling, so I look at the business and the lease together from the first conversation. Check the lease term and the assignment clause before you talk to buyers.

The problem
Plenty of good businesses don’t sell for what they’re worth, or don’t sell at all. Buyers walk away when the books aren’t clean, the business depends too much on the owner, or one customer is too big a share of sales.
And the real estate can kill a deal late: a landlord who won’t consent to an assignment, a lease with too little term left, or a property question nobody looked at early.
What I do about it
I start with a confidential look at the business and the real estate together, so the things that make buyers nervous get fixed before they ever see them. I know what active buyers are looking for, I help you get the business ready, and I handle the lease or property side, which is where a lot of sales get stuck.
Everything goes through Coldwell Banker Prestige Realty and is agreed in writing first.
Ready now or planning ahead, the first step is the same. See succession planning for what happens on the first call, realistic timing and what to gather.
What buyers in this space look for
- A lease with real time left on it. Buyers want enough term to earn back what they pay you, plus options to renew. A short lease can sink the price.
- The kitchen and the permits. Venting, grease traps, gas, the health permit and the liquor licence if you have one. Each one is expensive or slow to replace.
- Steady sales they can verify. Sales records that match the bank deposits and the tax filings.
- Staff who stay, especially the kitchen lead.
- A concept that works without you. If you are the chef and the host, buyers will discount for that or ask you to stay on.
Why and when owners sell
Burnout is common in food, and so is a partner who wants out. Others are ready for a new concept or retirement. Start before the lease gets short.
With three or more years left, plus an option, you have far more buyers.
How a confidential sale works
- A first conversation. Just us. What you have, what you want and when.
- A quiet look at the business and the real estate. I can tell you what buyers are likely to like and where they’ll push.
- Getting ready. Statements, the lease or property, a list of what’s included. Your accountant and lawyer come in early.
- Approaching buyers carefully. A short, anonymous summary first. Details only after a confidentiality agreement, and only to buyers you’re comfortable with.
- Offers and due diligence. Usually a letter of intent, then a closer look at the books, contracts, staff, equipment and the lease.
- The lease or property. Landlord consent and a release, or the property terms if you own the building. This is where deals often stall, so I start on it early.
- Closing and handover. Many owners stay on for a set period to help with the transition, if they want to.
Where the real estate fits
Most restaurant sales are really a lease assignment plus the equipment and the name. The landlord has to consent, and many will want to see the buyer’s experience and finances. Some will ask for a new lease or a higher rent.
I start that conversation early so it doesn’t surprise you at the end. Any work I do on a sale is through Coldwell Banker Prestige Realty and agreed in writing first. Where the sale is shares only, with no real estate, I’ll say so up front and work with your lawyer and accountant on those parts.
Where everybody wins
You want a fair price, care for your staff and customers, and a clean exit. A buyer wants a well-run business they can trust, with a lease or property that supports it. A landlord wants a strong new tenant.
When the business is ready and the real estate is sorted early, all three can say yes.
Questions people ask
How are restaurants valued when they sell?
Usually on the profit a buyer can expect, plus what the kitchen, the location and the lease are worth to them. A busy room on a short lease can sell for less than a quieter one with ten years left.
Does my landlord have to agree to the sale?
Usually yes, if the buyer is taking over your lease. Most leases need landlord consent to an assignment. Read yours, and talk to your lawyer about getting released from future liability.
Can I sell my restaurant without my staff finding out?
Early conversations can happen without naming the business, and details only go to buyers who sign a confidentiality agreement.
What should I gather, ask and watch for?
Documents to gather
- Three years of financial statements and tax returns
- The lease and every amendment, or title if you own
- Liquor licence, health inspections and equipment list
- Shareholder agreement and corporate records
Questions to ask
- Share sale or asset sale, and the tax on each? (ask your accountant)
- Will the landlord consent to assigning the lease?
- Do my shares qualify for the lifetime capital gains exemption?
- How long will I stay on after the sale?
Common mistakes
- Starting with too little term left on the lease
- Messy books that buyers can’t follow
- Telling staff or customers too early
- Leaving the tax planning until after a deal is signed
Typical timeline
- 1 to 3 years beforeClean up books, extend the lease, plan tax
- Months 1 to 3Prepare the package; confidential marketing
- Letter of intent to due diligenceOften 30 to 90 days
- ClosingLandlord consent, lawyers, transition
Typical ranges. Your lease, lender and the City set the real dates.
Go deeper
If you’re looking for more details
What buyers ask first in this industry
The lease term, the kitchen equipment list, the health permit and any liquor licence, and sales records that match deposits.
A preparation checklist
- Three years of clean financial statements
- A list of what’s included: equipment, vehicles, inventory, contracts
- Your lease, or the property details if you own
- Any permits or licences the business needs
- A short list of what only you do, and a plan to hand it over
What usually slows a sale down
- Books that don’t match the tax returns
- A landlord who hasn’t been asked about consent
- Customers or suppliers tied only to the owner
- An environmental question nobody looked at
Working with me
Why work with me
I go and find buyers
I talk regularly with buyers who are looking for BC businesses, and I go out looking for the right fit.
I learn the business first
How it makes money, what it needs from its space and what the next five years look like. The real estate should fit the business.
Advertising and communications since 2010
I’ve worked in advertising and communications since 2010. Your requirement, or your business, gets presented with real strategy.
Calm when things heat up
Over 10 years as a volunteer firefighter and first responder. When a deal starts to feel like it’s on fire, I’m the steady one in the room.
Confidential by default
Nothing about you or your business gets shared without your say-so.
You can trust me
I tell you the truth about your deal, even when it isn’t what you hoped to hear. If I say I’ll do something, I do it.
Search
Not quite your situation? Search
Next step
Selling now or later, the first call is confidential.
Give me a shout anytime. The first conversation is confidential, and there’s no cost to it.